Investment Return (40.74 vs. 20.22)

On 40.74, IR = NII - Provision for Credit Losses
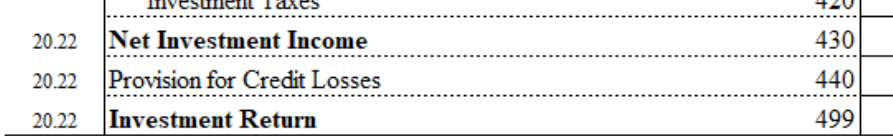
On 20.22, the Investment Return is surrounded by additional items:
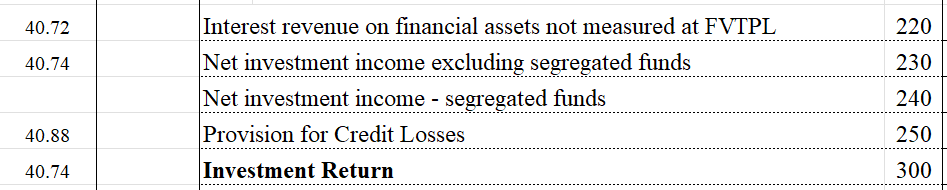
I wanted to understand how the following incorporated into the calculation:
- Interest revenue on financial assets not measured at FVTPL
- Net investment income excluding segregated funds
- Net investment income - segregated funds
Furthermore, how do the formulas reconcile between 40.74 and 20.22?
Thanks 
Comments
Interest revenue on financial assets comes from 40.72
Both the net investment income items comes from page 40.74. I think the allocation of the sub items between segregated funds and non-segregated funds is an accounting thing and is not needed for this exam
Thanks for your reply. I'm still unsure on this. It seems to me that:
40.74.499 "Investment return" is fully done on 40.74 as sum of line items:
On 20.22, Investment Return isn't actually calculated - it's just equal to 40.74.499 (Investment Return).
An implication of above: Suppose we are given all the values on 40.74, but we are also given "Interest revenue on financial assets not measured at FVTPL", "NII excl SF", "NII - SF". To calculate Investment Return, we would ignore these additional three values.
Please let me know if this all correct. Thanks again.